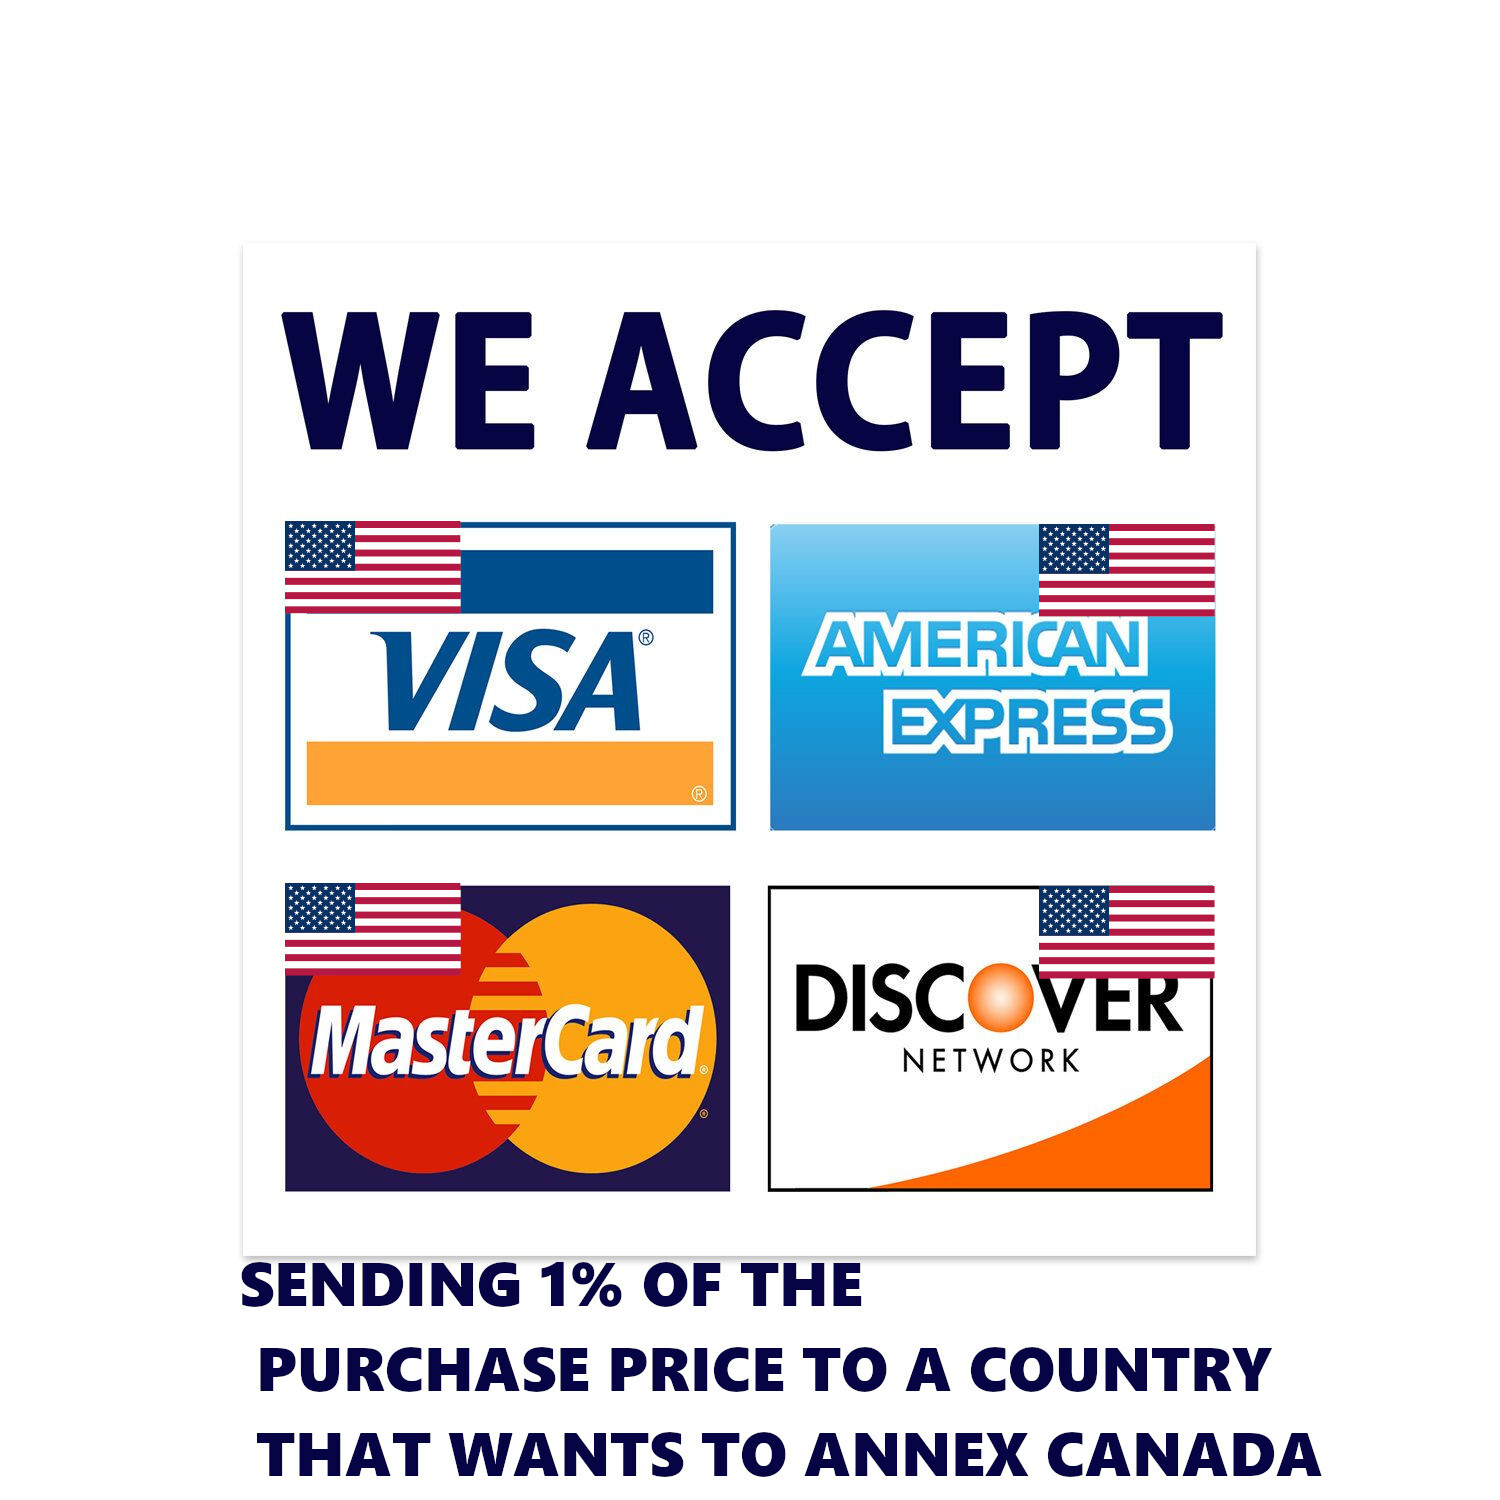
Visa and Mastercard are American companies, and they essentially tax everybody by taking a percentage of purchase prices for themselves. Not exactly a small percentage either, 1.2% to 2.65%. Ever wonder why so many merchants say they don’t accept American Express? That’s because they charge quite a bit more to merchantes, 50% more than Visa or Mastercard. Anyway, we’re letting American companies tax us and we love them because we get rewards when we use cards. But it’s just a shell game because we pay more up front because businesses need to charge more to make up for payment processing charges. They get to sit in the middle and rake in the money.
Now the alternative in Canada is Interac. Interac charges a set amount per transcation. How much? 2 to 5.5 cents. Unless you’re going through Apple or Google Pay, and then it’s a percentage again.
Interac is also Canadian.
Want to stick it to Trump? Stop using credit cards (and Google Pay or Apple Pay) and switch to Interac. Want to make Canada better? Stop using credit cards and switch to Interac. Is it going to be inconvenient? Yes. Online shopping will be much harder but I have seen online Interac payments before and we can ask our favourite Canadian merchants to accept Interac online.
I have a cash back VISA card. The week after Jan 20, I pulled my card info off every online service I use, stopped using the card entirely, and a few days ago canceled it completely. It was a tough choice. I generally earned about $600 a year cash back, but it’s time to free ourselves of America and forge our own path. I don’t really see the Can/American relationship ever being repaired at this point. Time to move on.
I’m on board for this but this proposal is up against a familiar devil: the network effect.
Shops support Visa and Mastercard because customers use them, customers use them because shops support them. This creates a powerful network that is extremely difficult for an upstart to unseat.
So while it’s a good idea to encourage people to take individual action on this — and you’re doing a great job doing so, and I’m taking it to heart for my own actions — we also need to accompany this with a policy solution to help overcome the network effect.
You’re right and the network effect would be very hard to overcome for this. It would need a lot of media attention just like liquor and alcohol.
I whipped this up too.
This is super cool. And you’ve inspired this Canadian to start moving more payments to Interac. Love the message and I’m on board.
My suggestion to accompany this with policy is not an alternative to taking personal action, but complementary.
One piece of constructive feedback on the artwork— it might be helpful to stress the positive aspect front and centre. For example lead with Interac with a maple leaf, and the American systems in lower prominence by having them 2/3 sized and positioned below.
Please don’t misconstrue my feedback in your mind as an attempt to distract or demoralize you through bike-shedding or anything like that. You’re doing great stuff and it’s inspiring.
I have the same question as sloppychops. If my interac debit card is also Visa, how would I know whether the payment terminal is routing through Visa or Interac?
I am one who offers to pay in cash sometimes to small businesses, treating it like an additional tip. But more and more businesses in the Vancouver area use Clover (A Canadian subsidiary owned by Wells Fargo) and Square (American fintech), and either take card only (which they get their cut with Interac debit too), or the staff get a little impatient when I rummage around for cash in my wallet.
Same with mastercard.
The Canadian banks are big enough to build a wholly Canadian credit system for global use, especially if they could get everyone in Canada (and maybe elsewhere) to switch right now.
They probably get too many incentives from Visa and Mastercard to find it enticing though, which is why they’re always pushing credit cards and offering cashback and airmiles, etc.
I think there is a European alternative being developed. Perhaps we can get in on that.
What happens if your card is Interac and Visa debit?
This is a brilliant strategy. Thank you for sharing that.
When I was paying at a local shop recently, I mentioned to the owner I’m trying to pay cash now rather than card because Visa is a US company and he he thanked me, since using a credit card costs them money.
It’s not all or nothing as you have options folks:
-
If you still want to use credit cards to increase your credit rating and to receive the cashback you can just Interac/cash/direct deposit for small businesses and charities then use the credit cards for the big guys.
-
You can also just boycott Visa, Mastercard, American Express and Discover for the duration of the trade war or the Trump presidency.
Sometimes incremental change is the way to go.
Additional information from Goodsuniteus on the political contributions of the credit processors:
Visa: 51% democrat / 49% republican / very high contribution level.
Mastercard: 56% democrat / 44% republican / very high contribution level.
American Express: 56% democrat / 44% republican / very high contribution level.
Discover: 72% democrat / 28% republican / very high contribution level. (May be acquired by Capital One)
Capitol One: 48% democrat / 52% republican / contribution level very high.
PayPal: 66% democrat / 34% republican / contribution level high.
Apple Pay: 85% democrat / 15% republican / contribution level very high.
Google Pay: 85% democrat / 15% republican / contribution level very high.
Samsung Pay: 63% democrat / 37% republican / contribution level medium. (At least South Korean)
-
For this to work, Interac needs to incentivize using it like credit cards do.
All types of loans require a credit score of some kind, and credit cards are one of the best ways to build this. Additionally, credit cards usually offer some kind of return.
Also because of poverty, a lot of people have a dependency on credit or payment plans.
Interac needs to make a Canadian answer to the credit card.
You can get a line of credit from your local bank, tranfser the available funds into your checking account on demand, then use your Interac card. The amount and rates are variable, so you can start with a small amount with a high rate (like starter credit cards), and as you build a reputation, you can be loaned larger amounts at a better rate. No third party credit card company required.
This is definitely one of the biggest hurdles with getting rid of credit cards, the lack of easy credit history.
Going the line of credit route is ok, but there’s no grace period before interest is charged, unlike most credit cards. So it’s something to be aware of.
Part of the problem for me is that paying interest to RBC, BMO, Scotiabank, TD, CIBC, BN in place of American payment networks when they aren’t really hurting for money, is not really helpful or impactful for anyone except for me in a negative way.
Credit unions do exist, and they keep money in the community much better than the big banks do.
The main reason to ditch Visa and Mastercard is hopefully if they get hit hard enough they’ll lean on Trump to shut up about annexing Canada. Greenland and Panama too.
I’m European. We don’t get credit card benefits, we just get stolen from. Everyone uses them nonetheless.
Oh wow no cash back at all??
What is it? You always pay the exact amount, why any cash (change) back?
On a lot of credit cards you get rewards for using them, like interest income. Basically the more you use it, the more interest you get, and you’ll get a credit in your account annually.
Some cards have different rewards like 2% back on all grocery spending for example.
Oh, we don’t have that. Nor air miles. Nor easy refunds.
I suppose the “richer” Europeans do though, I heard it referenced in an English movie of the same name.
Also, we never used checks, pretty much. Probably contributed to the explosion of CC use in the 90s despite the lack of benefits.
That’s very interesting, I learned something new today!
I’ve only ever used a debit card when I was in Europe. There was zero incentive to get a credit card. Moving in the US was different, I needed to build credit and cards were the best way.
Now I have a Prime card because 90%+ of my spending is on Amazon and at Whole Foods, both of which give 5% cash back. I get thousands every year, something really hard to give up. I wish I could stop giving Bezos money, but the convenience of Amazon is just too much of an advantage for me. And I know that shopping is now just a drop in their earnings compared to AWS.